Roofing and Siding Financing Options for Every Homeowner
Find a Roofing Contractor With Payment Options
Start with a written estimate, then ask what financing the contractor offers. Compare the APR, fees, monthly payment, and total cost with a loan from your bank or credit union. Before you apply, ask whether checking your options affects your credit score and when payments begin.
Financing can help you fix a leak or replace worn siding without paying the full cost at once. But the best plan is one that fits your budget and comes from a contractor you trust.
I'm Bill Hogan, owner of Hogan Roof, and I've spent over 20 years helping homeowners across NY, NJ, and CT with roofing, siding, and gutters. I know why people seek roofing contractors with financing: they need reliable work and a clear way to pay for it.
Roofing contractors with financing terms at a glance:
Why Working with Roofing Contractors with Financing Makes Sense
A major exterior remodel or an emergency roof replacement rarely happens when it is convenient for your checking account. On average, homeowners pay around $9,500 for a standard asphalt roof replacement, with complex architecture or premium materials easily pushing project totals beyond $45,000. When severe weather hits, waiting months to save up cash simply is not an option.
Working directly with certified contractors who provide structured payment solutions gives you immediate buying power. Instead of draining emergency reserves or waiting on slow insurance payouts, financing allows you to spread the investment across predictable, budget-friendly installments. Whether you are searching for roofers near me with financing for every budget or managing unexpected storm repairs, integrated contractor financing simplifies the entire exterior remodeling process while keeping your family safe and dry.
Fast-Tracking Urgent Roof and Siding Repairs
Water intrusion does not wait for ideal financial timing. A missing section of shingles or cracked exterior siding can lead to severe structural rot, ruined drywall, attic insulation damage, and hazardous mold growth in just a few days.
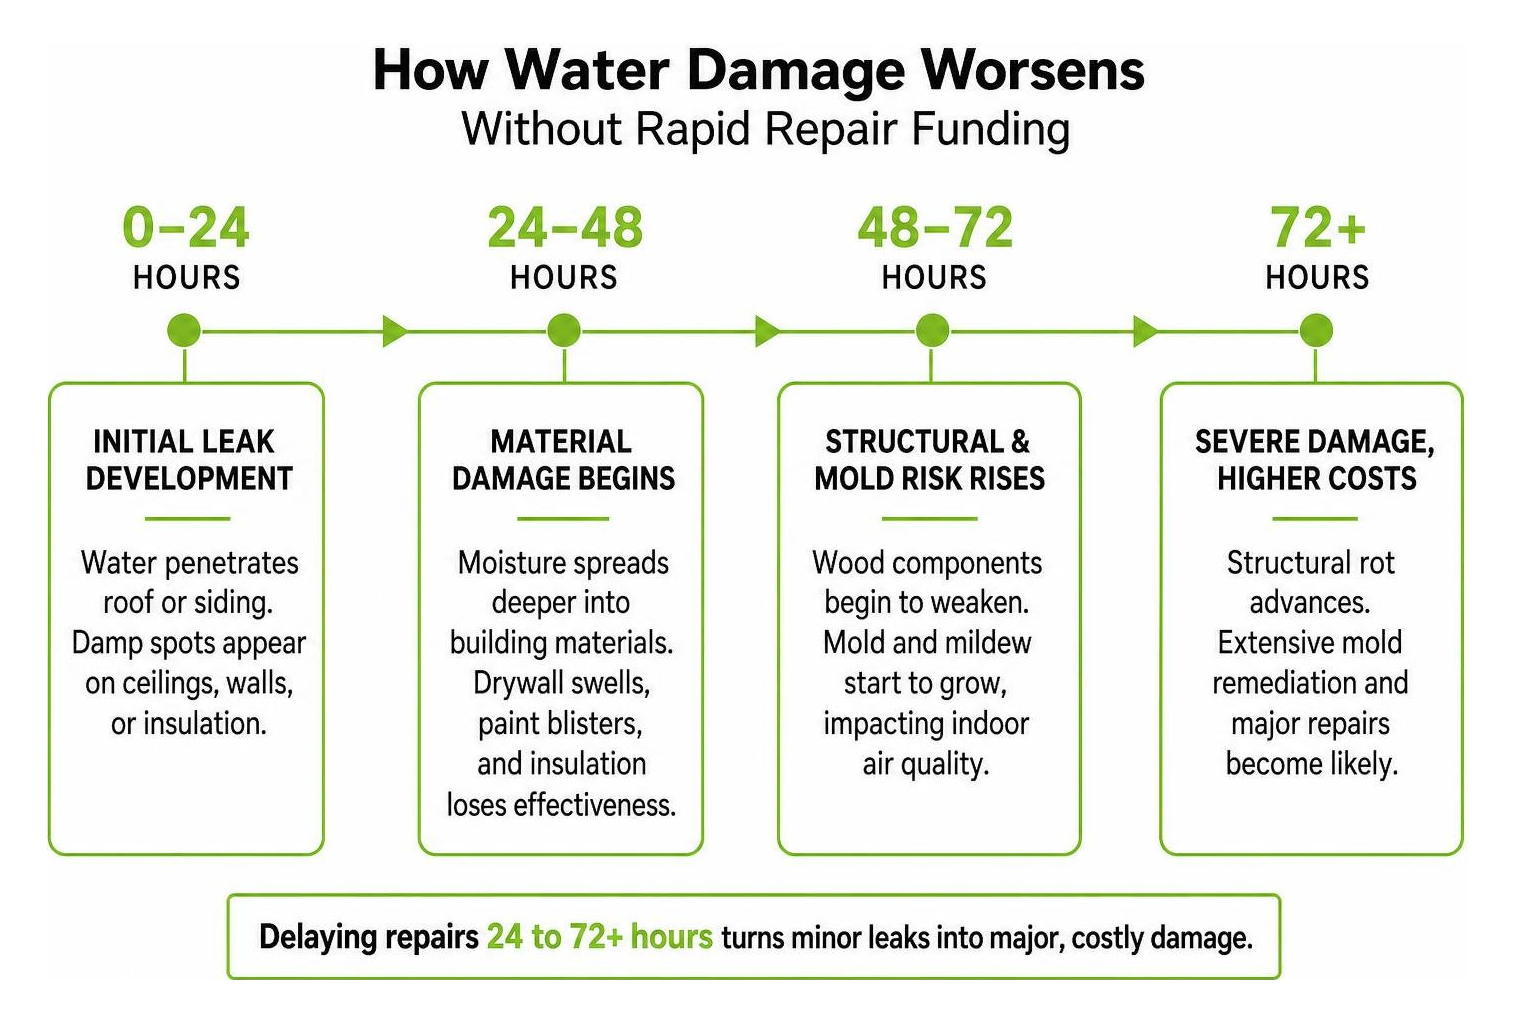
When you partner with a roofing company that offers integrated financing, approval decisions happen digitally in minutes. Rather than waiting weeks for traditional bank processing, many personal and home improvement loans disburse funds within 24 hours. This rapid funding allows our crews to mobilize immediately, perform temporary dry-ins, and execute permanent structural repairs before minor leaks spiral into catastrophic five-figure interior damages.
Upgrading Materials and Expanding Scope Without Upfront Cash
Settling for basic materials because of short-term cash constraints often costs more over time. Modern exterior upgrades—such as lifetime architectural shingles, impact-resistant shingles, fiber cement siding, and seamless gutter systems—offer superior durability and curb appeal.
Industry data shows that a quality roof replacement adds roughly $14,000 to a home's resale value on average. When you break project costs into manageable monthly payments, you can easily upgrade to durable systems like standing seam panels. For homeowners interested in premium, long-lasting alternatives, exploring top companies offering metal roofing payment plans can make superior energy efficiency and 50-year longevity surprisingly affordable.
Comparing Roofing and Siding Payment Options
Homeowners have multiple financing avenues to fund exterior renovations. Understanding the trade-offs between speed, total interest expense, closing requirements, and collateral helps you select the best vehicle for your household.
| Financing Method | Typical APR Range | Approval Speed | Collateral Required? | Best Used For |
|---|---|---|---|---|
| Contractor-Partnered Loans | 0.00% – 19.99% | Minutes to 24 Hours | No (Unsecured) | Fast emergency repairs, bundled roof & siding upgrades |
| Personal Loans | 6.00% – 35.99% | 24 to 48 Hours | No (Unsecured) | Mid-range repairs without dipping into home equity |
| Home Equity Line (HELOC) | Variable Prime + Margin | 2 to 6 Weeks | Yes (Home Equity) | Large phased remodels where you need multi-year draw access |
| Home Equity Loan | Fixed 7.00% – 12.00% | 2 to 6 Weeks | Yes (Home Equity) | Planned full replacements with substantial home equity |
| 0% Promotional Credit Card | 0% Intro (then 18%+) | Instant | No (Unsecured) | Small patching jobs or deductible coverage paid within 12 months |
Contractor-Partnered Financing vs. Traditional Home Equity Loans
Home equity loans and Home Equity Lines of Credit (HELOCs) are secured by your residence. Because the lender holds your home as collateral, they typically offer lower interest rates and allow you to borrow up to 80% to 90% of your home's appraised equity. Additionally, interest paid on home equity borrowing may be tax-deductible when funds are used specifically to buy, build, or substantially improve the home securing the loan (always consult a certified tax professional to verify your eligibility).
However, secured loans carry significant drawbacks:
- Lengthy Approval Timelines: Underwriting, formal appraisals, and title searches generally take between two and six weeks.
- Closing Costs: Appraisal fees, origination charges, and recording fees add hundreds or thousands of dollars to the upfront expense.
- Foreclosure Risk: Defaulting on a secured equity loan puts your property at risk.
Contractor-partnered financing utilizes unsecured home improvement installment loans. There are zero appraisal delays, no closing fees, and no liens placed against your property deed. When active leaks demand immediate action, the speed of unsecured financing heavily outweighs the lower rate of a slow-moving equity line. For a broader look at how installment lending works, the Consumer Financial Protection Bureau explains the basics of installment loans and repayment structures.
Personal Loans and Promotional Same-As-Cash Terms
Contractor financing partners frequently provide specialized loan structures, such as 12-month same-as-cash or deferred-interest programs. If you anticipate receiving an insurance reimbursement, an upcoming bonus, or a tax refund, these plans let you complete your exterior project immediately without paying any finance charges—provided the balance is paid in full before the promotional window closes.
For standard installment agreements, fixed terms spread payments evenly over set amortization schedules. Before signing any contract, using a loan calculator for your next major home project allows you to model monthly payments across various repayment lengths and interest rates to ensure comfortable cash flow.
Understanding Approval Criteria, Credit Scores, and Loan Terms
Applying for home improvement financing has evolved into a streamlined, transparent process. Lending platforms evaluate basic financial markers to match homeowners with viable lending tiers.
How Roofing Contractors with Financing Structure Loans and Repayment Terms
Professional contractors team up with established home improvement lending networks—such as Regions Bank, Sunlight Financial, and Foundation Finance—to provide loan limits reaching up to $100,000. Loan terms generally span from 3 to 12 years (and up to 15 years for high-ticket full-envelope replacements), giving homeowners the flexibility to balance loan duration against monthly costs.
When evaluating financing proposals, always verify that the agreement includes:
- Zero Prepayment Penalties: The freedom to make extra principal payments or settle the loan early without punitive charges.
- Fixed Interest Rates: Consistent monthly payments that never increase over the lifespan of the loan.
- Transparent Dealer Fees: Reputable contractors work with transparent lenders to provide competitive terms without burying hidden surcharges in your material bids.
Many local homeowners benefit from structured solutions; see our guide on working with roofers that take payments without breaking the bank for additional insights on budgeting strategies.
Qualifying for Roof Financing with Low or Fair Credit
A pristine credit score is not an absolute requirement to secure exterior remodeling funds. While prime rates are typically reserved for FICO scores of 640 and above, contractor lending networks offer flexible underwriting tiers:
- Prime Credit (680+ FICO): Unlocks the lowest fixed APRs and extended repayment terms up to 12–15 years.
- Near-Prime Credit (600–679 FICO): Solid approvals with competitive interest rates and straightforward electronic signatures.
- Subprime & Second-Chance Programs (550–599 FICO): Specialized financing programs can approve applicants with scores down to 550 by evaluating stable income and debt-to-income (DTI) ratios.
Most modern contractor portals utilize soft credit checks for the initial pre-qualification phase. This allows you to view available rates, payment tiers, and loan amounts without impacting your credit score. If your credit needs support, adding a creditworthy co-borrower can substantially improve terms and secure lower interest rates. Homeowners seeking specialized installations can also evaluate local metal roofing financing options for homeowners to find tier-friendly programs.
How to Secure Financing and Start Your Exterior Remodeling Project
Financing an exterior remodel should be straightforward and stress-free. Partnering with an experienced, certified installer ensures the project runs smoothly from initial inspection to final clean-up.
Tips for Choosing the Right Roofing Contractors with Financing
Financing is only as reliable as the contractor executing the physical installation. Protect your investment by partnering with proven industry professionals:
- Verify Manufacturer Credentials: Top-tier designations, such as Owens Corning Platinum Preferred Contractor status, demonstrate advanced craftsmanship, financial stability, and the ability to offer extended manufacturer warranties.
- Review Full Licensing and Insurance: Ensure the company carries comprehensive general liability and workers' compensation coverage across NY, NJ, and CT.
- Insist on Detailed Written Scope: Avoid vague quotes. Your estimate should itemize tear-off, underlayment, flashing, ventilation, siding wrap, and cleanup.
- Transparent Communication: A reputable contractor answers financing questions clearly, without aggressive on-the-spot sales pressure.
If you are beginning your planning process, you can receive an instant roof quote online to establish a realistic baseline budget.
Step-by-Step Guide to Applying for Contractor Roof Loans
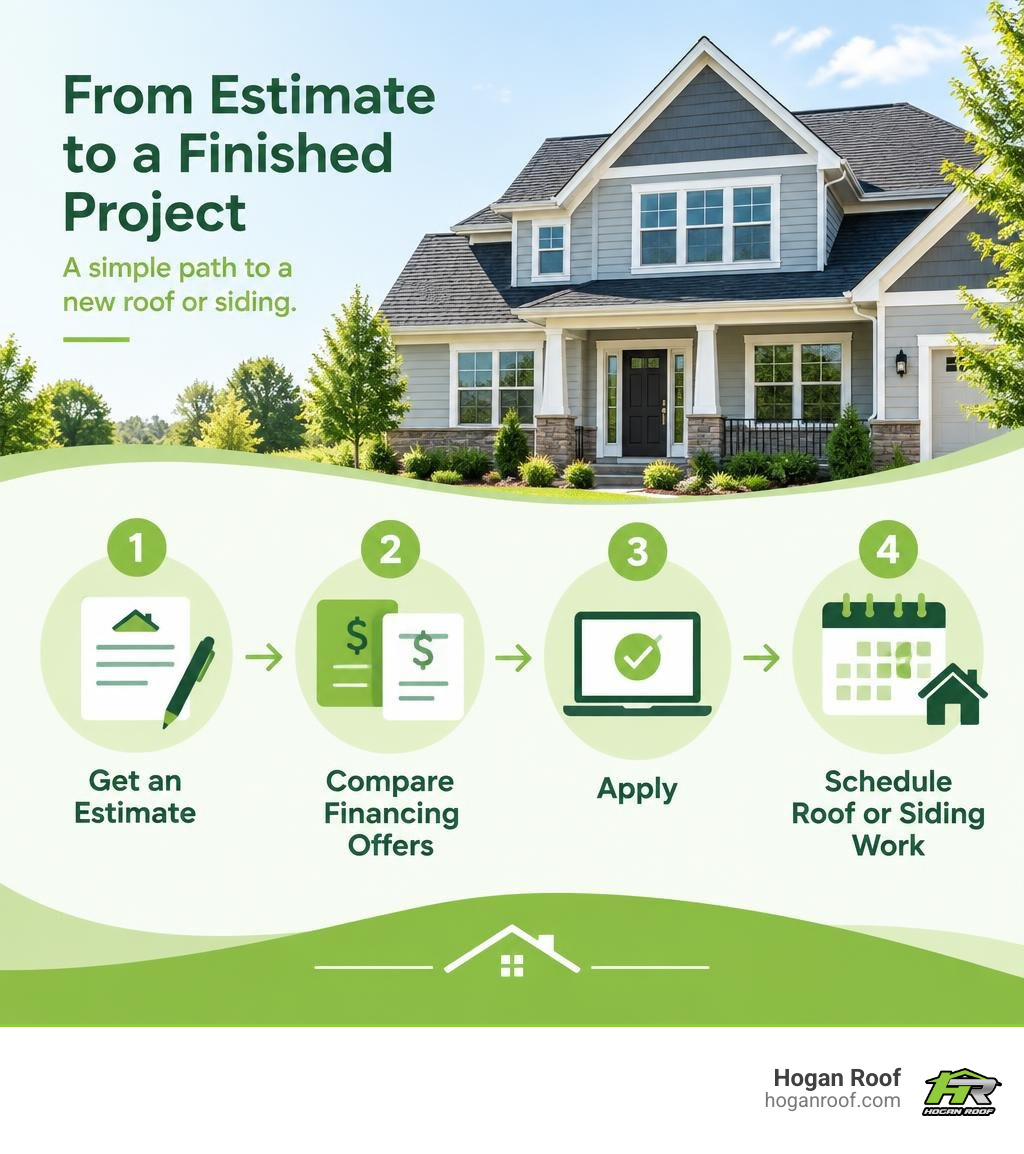
Securing financing through your exterior contractor follows a simple four-step process:
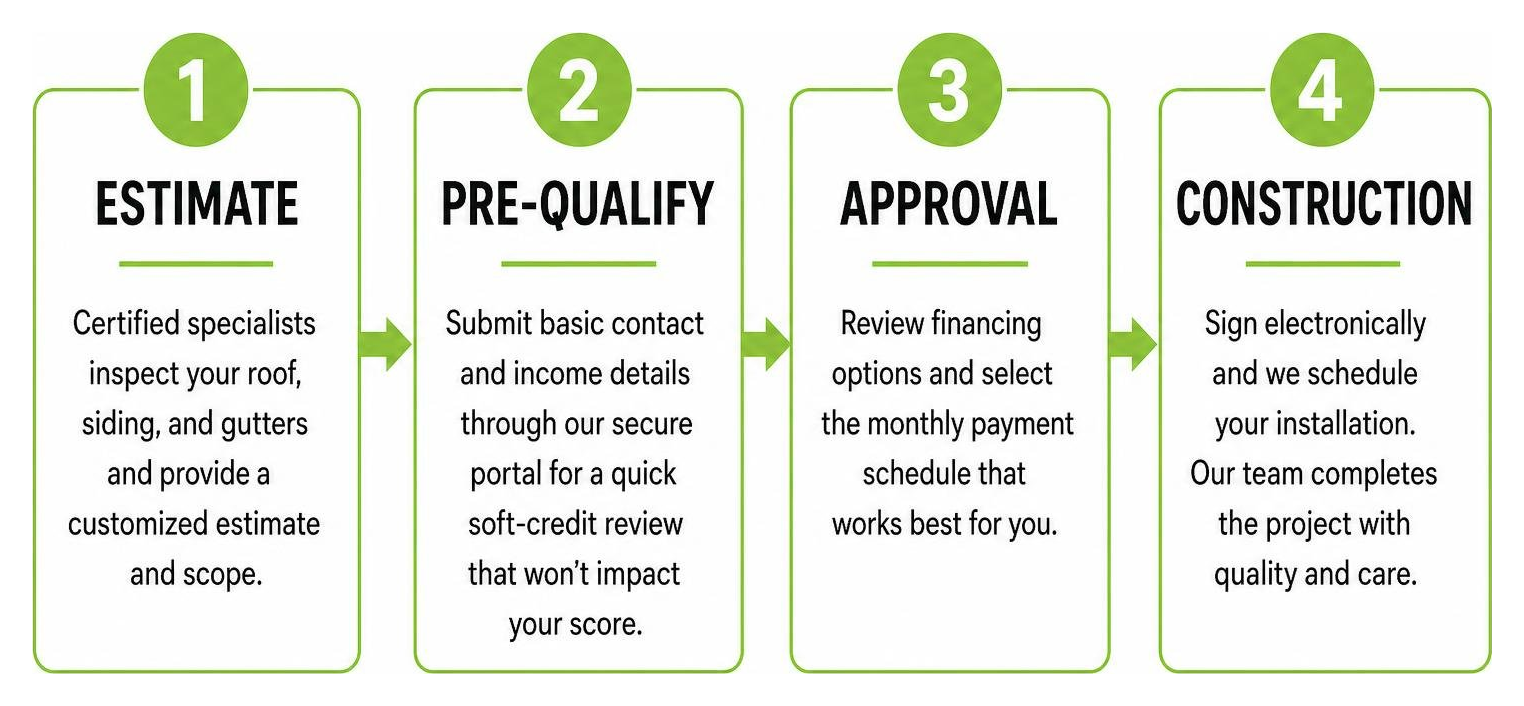
- Comprehensive Property Inspection: Our certified specialists inspect your roof, siding, and gutters, identifying storm damage, ventilation issues, or age-related wear.
- Customized Estimate & Scope: We present a detailed proposal offering Good/Better/Best material configurations suited to your architecture and budget.
- Digital Pre-Qualification: Using our secure mobile portal, you submit basic contact and income details for a 60-second soft-pull credit review that does not affect your credit score.
- Loan Selection & Electronic Signature: You select the monthly payment schedule that suits your needs, complete the electronic paperwork, and we schedule your installation.
For tailored guidance, you can contact our regional team directly to schedule a free on-site assessment.
Frequently Asked Questions About Roof and Siding Financing
What credit score do I need to qualify for roofing financing?
Most unsecured home improvement lenders prefer a credit score of 640 or higher for their most competitive interest rates. However, flexible financing partners provide second-chance programs with approvals down to a 550 FICO score. Factors like steady employment, verifiable household income, and a reasonable debt-to-income ratio play significant roles in approval decisions.
How fast can I get approved and funded for a roof replacement?
Digital applications typically deliver credit decisions in 60 seconds. Once you review and electronically sign loan documents, funding is often authorized within 24 hours. This rapid turnaround allows contractors to order materials and begin urgent storm repairs immediately.
Can I use contractor financing to cover my insurance deductible?
Yes. While state laws require homeowners to pay their required insurance property deductibles out of pocket, you can utilize an unsecured home improvement loan or short-term payment plan to cover that deductible legally and comfortably. Financing is also commonly used to fund elective upgrades that insurance claims do not cover, such as switching from basic 3-tab shingles to lifetime architectural shingles or adding premium siding insulation.
Conclusion
A compromised roof or deteriorating siding threatens the structural integrity, safety, and energy efficiency of your home. You do not need to postpone vital exterior restorations due to upfront cost concerns. By partnering with experienced, manufacturer-certified contractors who provide flexible lending solutions, you can protect your home today while enjoying affordable monthly installments.
With over two decades of dedicated service across New York, New Jersey, and Connecticut, Hogan Roof provides high-quality residential and commercial roofing, siding, and gutter installations. Explore our flexible financing options today to design a payment plan tailored to your budget and secure lasting protection for your property.